
Last Updated: September 4, 2026
Table of Contents
Introduction – Netweb Technologies Share Price Target 2030
The Netweb Technologies share price target 2030 is a very different question from a 2026 one. The company has four years, rather than two, to develop, but that also means there is much more unknown.
Netweb Technologies’ key market segments are likely to stay relevant for most of the decade since they include AI infrastructure, high-performance computing, private cloud and data center & enterprise computing. The company has also seen a fast-growing demand for it’sAI Systemsbusiness.
The numbers up to date reveal the magnitude of that growth. In the Q1 FY27, Netweb has announced a revenue of operating of the approximately 819.6 crores while this number was around 301.2 crores in the same quarter of FY26; also Netweb’s Profit after Tax has grown to 85.32 crores compared to 30.4 crores in Q1 of FY26. The contribution of AI System segment of Netweb Finance Ltd to the revenue of the company has been of 510.57 crores (62.29%) which has grown to 484.2%. Downward, the order book of Netweb as of 30 June 2026 has been of 2,507 crores.
Those stats certainly make the long-term tale intriguing. They certainly do not, however, make a share-price prediction for 2030 definitive.
Therefore this article considers Netweb’s 2030 target through business growth, earnings, industry demand, valuation and other realistic scenarios rather than staking all one exact number for a guaranteed outcome.
Please note: This article is for educational and research use only. Share-price targets are merely estimates, based on presuppositions and may vary widely. It is neither financial opinion nor a suggestion to buy/sell Netweb Technologies stocks.
What services does Netweb Technologies provide?
Netweb Technologies India is an Indian technological company dedicated to high end computing infrastructure.
Its business includes:
- Advanced computing systems
- AI computing systems;
- Private cloud infrastructure The architecture of a private (internal) cloud allows it to have much same flexibility and independence as the public cloud model, based on three common concepts.
- Data center solutions What we are doing is: Data center.
- Enterprise servers
- Storage solutions
- Networking infrastructure
The company’s standing in AI infrastructure is vital for its long-term vision.
AI applications demand significant computing resources. companies, research facilities, cloud providers and government bodies. need the servers and other infrastructure for those loads.
Thus, ãThis establishes a potential long-term market for firms who can design, integrate and produce those systems within India.
Why 2030 Could Be Important for Netweb
A 2030 forecast, however, is not just an extension of the current share price.
By 2030, several things could be very different:
- Nextweb’s revenue had the potential to be considerably larger.
- If this is the case, then the potential for AI to consume even larger proportion of computer resources increases.
- There is the possibility of an increase in the capacity of data centers.
- It is possible that the spectrum of customers of the company may be widened.
- Possible to generates revenue from new products.
- The competition can be more severe.
- The company’s valuation might be significantly different.
Therefore, a long-term target should be based on future earnings and valuation rather than the present market price.
Netweb’s Current Growth Story
The results for the company were quite recent and serve as a good starting point for any long term analysis
| Metric | Q1 FY26 | Q1 FY27 | YoY Change |
| Operating revenue, or turnover. | ₹301.2 crore | ₹819.6 crore | +172.1% |
| Stand-alone profit after tax. Calculation for profits after tax generated by each project, unit, and product is calculated on a stand-alone basis. | ₹30.4 crore | ₹85.3 crore | +180% |
| AI Systems revenue | ₹87.4 crore* | ₹510.6 crore | +484.2% |
| Order book | — | ₹2,507 crore | — |
Reported segment profit reported by the company in Q 1 FY 26.
The numbers demonstrate a real momentum, but one should be cautious about multiplying by existing trends forward to 2030.
Growth beyond triple digits does get exponentially more difficult to sustain as a company scales, and a rational long term model would be one that slowdown growth at some point despite continued success.
The Importance of AI Systems
All in all, AI Systems is the key driver of netweb’s growth story today.
Q1 FY27: Ledipasvir/Sofosbuvir, the second largest segment, accounted for more than 62 percent of operating revenue.
It’s a huge factor in where the company will be heading in 2030 that makes the future of AI infrastructure.
If businesses continue investing heavily in:
- AI training
- AI inference
- GPU servers
- Data centers
- Sovereign AI infrastructure
- High-performance computing
Netweb potentially has a larger market opportunity by the end of the decade.
But the reverse may also happen. If investment in AI infrastructure or execution of AI projects slows, or the pace of new customer implementation projects is delayed, the growth will not meet today’s expectations.
Order Book and Future Revenue
According to Netweb, order book for the end of June 2026 was around 2507 crore.
Somewhat reveals insight into business to come.
Nonetheless, investors should not make the mistake assuming that whole order book is a definite future income.
The more useful questions are:
- What is the value of lead time?
- What margins are these projects making?
- Are the orders new or replaced?
- Question 3 Is the customer base expanding and becoming more diversified?
- What represents the level of business being generated by the company?
Execution quality will be as important as the size of the order book.
Long-Term Growth Drivers
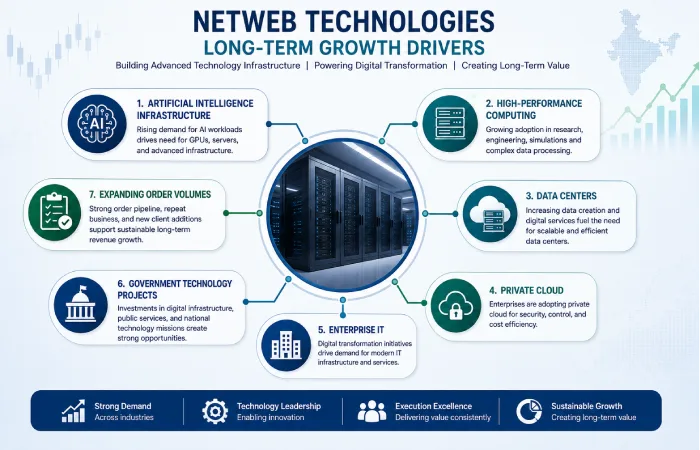
AI Infrastructure
The long term expansion of AI, could stay the biggest long term opportunity.
Computing power is expected to continue to be a necessary factor as AI models increased in complexity.
Data Centers
The way these cloud services, digital applications, and AI workloads are growing has driven the requirements for data center infrastructure.
Maybe develop opportunities across servers, storage, networking and integrated systems.
High-Performance Computing
HPC has its uses in other areas too.
It supports:
- Scientific research
- Engineering
- Weather modeling
- Financial analysis
- Government research
- Academic institutions
This would give a Netweb exposure to more than one market.
India’s Digital Infrastructure
India is increasingly growing its domestic technological infrastructure.
If there is an Indian manufacturer producing state of the art computing systems locally, this could open routes of entrance into government, enterprise, research and AI infrastructure projects
What are the steps that must be taken in order for the 2030 Story to be implemented?
A bullish 2030 scenario would assume the following options all played out:
Netweb would need to:
- Maintain good pace of revenue growth.
- Turn the order book into real sales.
- Define what is “reasonable profit” for your undertaking.
- Get more wins on AI and HPC projects.
- Design a progressive line of competing products.
- Broaden the number of customers.
- Manage working capital and cash flow prudently;
- Compete successfully as the large technology companies come in.
Hence why a 2030 target should not be seen as a direct prediction in the form of an estimate of where we would like to be.
Netweb Technologies is target for 2030 is Bull case, Base case and Bear case.
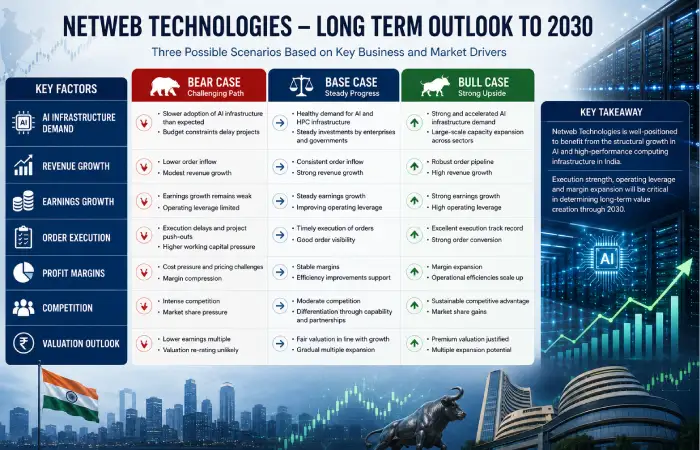
Those who attempt to provide a precise Netweb Technologies share price target for 2030 would be creating an illusion of accuracy. Technology is a fast-changing industry. In 4 years revenue can evolve, new challengers can come into the picture, spending on AIs can accelerate or decelerate and the value that investors are ready to allocate can vary vastly.
A more effective course of action involves constructing each of three possible outcomes and outlining what would have needed to occurred in order to reach any of the three.
Netwebs current numbers are a good baseline for us. In Q1 FY27, took in revenue of approx. 819.6 crores, PAT of approx. 85.3 crores and $510.6crores in AI Systems revenue. Its reported order book was approx. 2507 crores as of the 30 th of June 2026.
Meanwhile, published projections already demonstrate the extent of possible variation. A recent model indicated its 2030 median at about ₹3,944 with a very broad P10–P90 range of about ₹964 to ₹16,125. Far from being something to be blindly replicated, that is indicative of the high degree of uncertainty in any long-term projection.
Netweb Technologies 2030: Three Possible Scenarios
| Scenario | Long-Term View | Indicative 2030 Range |
| Bear Case | Slows growth and valuation falls | ₹3,000–₹4,000 |
| Base Case | A growth that is strong and sustainable | ₹5,000–₹7,000 |
| Bull Case | Growth in AI, HPhpc remains exceptional. | ₹8,000–₹10,000+ |
These are scenario bands; not targeting. They are used to demonstrate that different business opportunities can easily result in very different stock results.
[should be revisited?] After every major quarterly results, particularly as we approach FY28–FY30.
Bear Case: ₹3,000–₹4,000
The bear scenario assumes that Netweb is still a successful company, but the growth rate will be significantly lower than what investors are experiencing today.
That doesn’t necessarily imply the business is weaker. It just could be that a hyper growing environment will be get more competitive, and scale will be harder to achieve.
AI Spending Normalizes
Much of Netweb’s recent growth has been driven by the build-out of AI infrastructure. Should spend by cloud providers, vendors to enterprise, or government projects decrease then growth rates could suffer.
This is one of the major risks for the long-term story.
Margins Come Under Pressure
On netweb, Q3, FY26 operating EBITDA margins stood at 12.2%, down from 12.9% in the corresponding quarter last year. The company stated that this drop was driven by the execution of a large strategic order.
Thus a model long-term should not presume that revenue’s growth translates into equally robust profit growth.
Valuation Falls
This could be even more significant than revenue.
A stock can stay in an uptrend even as its share price is declining, if the market perceives that the company should be trading at a lower multiple.
With the bear case, slower growth and lower valuation could keep the stock in the 3,000–4,000 range by 2030.
Base Case: ₹5,000–₹7,000
In the base case I assume that Netweb’s growth will stay far above the growth of an average IT-hardware company, but that it will level off eventually as the company gets larger.
I would regard this as the balanced case, rather than just assuming that a continued 20% p.a. growth rate over the next four years.
For this range to make sense, Netweb would need:
- High need for AI infrastructure Successful implementation of in-depth application has resulted in a high demand for infrastructure of AI. There are many different levels of infrastructure needed.
- Continued HPC growth
- The regular order wins.36It is easy to see how large Congress is with 535 voting members. Holding 534 votes is only practical if very little debate is required. The vote will always win a vote, a decision that can be brought to the floor from committee by a motion to order and that is one of the most powerful actions available to a motion to order. So the more committee votes, the better.
- Efficient execution of orders.
- Stable margins
- Healthy growth in earnings
- Increasing scale
On the market front, there is already ample evidence that the company is in a large and growing market. Netweb’s presentation to investors points to AI GPU systems, HPC, data centers, private cloud and India’s growing sovereign AI ecosystem as key business tailwinds.
The results found for the base case therefore can be summarized by simply saying the AI opportunity persists but the game becomes significantly more competitive.
Bull Case: ₹8,000–₹10,000+
The bull case has Netweb becoming a very much larger and more profitable AI infrastructure company by the end of the decade.
In order for that to occur, certain conditions would have to be met:
AI Infrastructure Keeps Growing
If the rate of AI investment persists for years instead of only the present cycle of expenditure, demand for AI systems and high-performance computers will be sustained for Netweb.
Earnings Scale Faster
The company would have to translate its revenue growth into solid growth in earnings.
That means:
- Greater low level profits;
- Healthy EBITDA margins
- Enhanced operating efficiency
- Recent emergence of positive cash generating ability.
Large Customers Keep Coming
The government, enterprise, data-center and cloud customers could be a valuable source of repeat business.
Having more large customers would also curtail dependence on any one project.
Valuation Remains Premium
Likewise, even robust earnings would not guarantee a Rs8,000- Rs10,000 stock price.
Investors would also still need to value Netweb as a high-growth AI infrastructure business,
That is the most difficult part of any long-term target to forecast.
Revenue Growth Is the Key Number
When looking ahead to our 2030 forecast the key question is not what the share price is today.
It is:
What is the maximum size for Netweb’s revenue as of 2030?
In an earlier Equirus research report Netweb FY27 revenue was predicted at approx. ₹3,617cr with FY27 PAT at approx. ₹329cr while mentioned strong growth prospects but also highlighting need to monitor margins, working capital and free cash flow.
Those earlier estimates need not be taken as the forecast for today. Longer-term values have consistently increased above previous estimates with this company’s long-term values.
AI Is the Biggest Long-Term Opportunity
The mix of the company business has been evolving rapidly.
According to the release of results, the AI Systems composed approximately 64.2% of the revenue for Q3 FY26
That’s what puts the AI infrastructure market at the heart of the 2030 story.
If AI demand remains strong, Netweb could benefit from:
- GPU-based computing
- Training infrastructure for AI.
- Artificial Intelligence inference systems AI inference systems involve the core physics design;all the models of the various elements; the physics of the interactions; all the atmospheres and thus the all related physics codes;and the other physics codes such as the chemistry, the plasma physics etc.
- Sovereign AI projects
- High-performance computing
- Data-center expansion
But this also carries a concentration risk. If spending on AI were to take a turn for the worse, the consequences for Netweb could be severe.
The Data Center Opportunity
AIT certainly tells only a part of the tale.
Demand for data centre services, cloud services and processing of digital applications is rising in India which also raises the demand for physical IT infrastructure.
Netweb’s investor presentations point to high data-center demand in India and rising on-premise cloud infrastructure as business tailwinds.
This is important, because additional growth opportunities can be offered to the business.
Competition Will Matter More by 2030
One of the more common errors is to assume that a firm’s position today will look exactly the same five to ten years forward.
By 2030, Netweb could face stronger competition from:
- Worldwide server producers
- (Indian infrastructure companies)
- Cloud providers
- AI hardware companies.
- Technology start ups.
In a competitive market, customers may require a lower price or better service.
That could also cut into margins even if demand stays strong.
What Investors Should Watch Between Now and 2030
Rather than close the file and check the 2030 target every 3 weeks, keep track of the numbers after each report.
| Metric | Why It Matters |
| Revenue growth | Indicates if the company is growing |
| AI Systems revenue | Indicates how much is exposed to the most rapidly expanding part the means |
| PAT growth | Indicates if the growth is hitting the bottom line |
| EBITDA margin | Indicates whether profit is going strong. |
| Order book | Provides visibility into future business |
| Order execution | Indicates whether the booked projects generate revenue |
| Cash flow | Indicate the quality of earnings reported (1) |
| Customer mix | Shows diversification |
| Valuation | Decides how much investors are paying for growth |
This is enormously more beneficial than flickering a forecast of a long-term price.
Netweb Technologies Share Price Predictions 2030: Long Terminology,Potential Risks &Scenarios.
Do not see a 2030 stock target as a promise, see it as a long-term scenario. There are 4 unknowns in 4 years: AI spend, competitors, earnings growth, interestrates, valuation, transition of opportunities to revenue at Netweb.
So for now the base is reasonably solid. Netweb earned in Q1 FY27 Rs.819.6 crore and its profit was Rs.85.3 crore. Its AI systems book contributed for about Rs.510.6 crore which constitutes 62.29% of the revenue and had a good order book of Rs. 2,507 Crore (as on 30 th June 26).
That provides a robust base for the long-term story, however, those who buy should pay more attention to the next phase, rather than to moving on with the shortest quarter.
What may alter the outlook for 2030?
Fairly easy to find these largest factors.
AI Demand
Currently, the AI infrastructure represents the most potential growth driver of Netweb’s business.
The significant issue is if the current AI infrastructure investments roll into a dead end or slow down after bringing to end companies’ initial investments.
According to Netweb, key market opportunities have arisen from demand originating from India’s sovereign AI initiatives, neocloud companies and providers of cloud services.
If those projects continue growing in scope, the 2030 opportunity really expands.
Earnings Growth
The headlines always go to revenue growth, but earnings are likely to be more important to shareholders.
According to the latest reported figures, Netweb’s net profit after tax in Q1 FY27 has risen by around 180% compared to the previous quarter.
To achieve a strong 2030 result, the investor would want earnings to be building up over time rather than hitting one or two outsized quarters.
Order Execution
The rupees 2,507 crore order book that the company has offers good transparency, but it’s only worth giving some weightage once it’s executed and turned into revenues and profits.
Investors should therefore track:
- New order wins.
- Order conversion
- Delivery timelines
- Project margins
- Repeat business
A growing order book with strong execution would be far more of a positive indicator than order growth on its own.
Risks to the 2030 Outlook
AI Spending Could Slow
The largest upside/long-term risk is the same as the company’s.
If the pace of AI infrastructure spending weakens substantially, then Netweb could experience lower growth in its fastest growing segment.
A lower-growth environment would also put more pressure on valuation], a high valuation becomes more difficult to sustain.
Competition Could Increase
Netweb is not in the traditional market place, so the dependence of competitors that exists in the traditional market place may change relatively fast.
Existing large global companies, Indian technology firms and the emerging new A I infrastructure companies?
More competition could lead to:
- Lower pricing
- More sales costs (i.e. on running the wheel).
- Margin pressure
- Increasing investment requirements
Execution Risk
Fast growth also has its difficulties.
The third challenge is how to efficiently scale manufacturing,supply chains,engineering skills and after sales support without sacrificing quality and profitability.
Strong growth is only beneficial if the company is able to cope with it effectively.
Valuation Risk
This should, of course, be paid attention to.
A company’s share price depends on both:
How much it earns
and
How much investors are willing to pay for those earnings.
This analyst research illustrates the hype that has built. In July 2026 ICICI Securities bumped-up their oneyear target to 5,360 and used a 66x oneyear forward P/E in their valuation.
But it won’t be the same time in 2030 that Netweb would be traded on the same multiple.
In fact, the opposite might occur: earnings could rise rapidly, even though the multiple would decline as the firm would increase in size and the growth rate would converge to a more stable number.
This is why a long-term objective requires an assumption of earnings and an assumption of valuation.
What form of the bull case would be more realistic?
A bullish 2030 outlook would become more convincing if Netweb consistently shows:
| Signal | Why It Matters |
| Strong AI Systems growth | Sustains growing demand |
| Increase in the order book | Creates visibility into future revenue (easy identification of potential revenue) |
| Good order execution | TSR converts an inquiry into an order that actually results in a sale. |
| Stable margins | Com can be shown growth is profitable. |
| 3. Good cash flow, (i.e. positive cash flow, large cash inflows, steady cash inflow). | Validates the quality of earning |
| More customers | A, Decreases concentration risk, through broad diversification across a wide swathe of the market. |
| New products | Increases the size of the potential market |
| International expansion | Opens up further opportunities for growth |
And very importantly, alone it is meaningless. Its combination is what makes the difference.
What Should InvestorsWatch for over the next 17 years?
Rather than doing a monthly 2030 price target check, investors should be more keyed in to what the actual company is doing.
After each quarterly result, review:
Revenue
On the upside, is growth comfortable still weeping the wider IT Market in Infrastructure?
AI Systems
How is AI not just a bigger and more profitable component of the business?
EBITDA Margin
Is the company remaining profitable on the way up?
PAT
Are profits growing proportionately to revenues?
Order Book
Is the pipeline growing and are the orders being currently delivered on time?
Cash Flow
Is rapid expansion actually creating cash? Or is it just converting cash into working capital?
Valuation
Is the stock price going up quicker than earnings?
That final question is especially relevant for those investing over the long term.
Frequently Asked Questions
What is the Netweb Technologies stock price forecast for 2030?
Again, there is no sure single target for 2030.
Different scenarios should be considered for a long-term forecast because the revenues growth, earnings and valuation as well as market environment are likely to vary significantly over the next four years.
Is this a long-term investment in Netweb Technologies?
It depends on the investor’s purpose, risk, valuation.
The firm is exposed to attractive markets including AI infrastructure, high performance computing and data centers. However, it will encounter risks including competitive, execution and valuation.
Will Netweb Technologies be able to sustain growing until 2030?
Has very large potential markets to develop, especially in AI and advanced computing infrastructure. But it gets more difficult to sustain Very high growth for multiple years, as the size of revenue base of the firm increases.
Given this, investors should not expect all growth to simply normalize, but rather expect the current growth to level off.
What is the greatest threat to the Netweb Technologies 2030 scenario?
The biggest risk is likely a marriage of slower AI infrastructure investment and valuation headwinds.
If the market takes the view that such growth warrants a lower valuation, then the company could continue to grow while the share price goes down.
Should I consider online 2030 (19,20) price forecasts for investment decisions?
No.
Long-term stock prediction website can give ideas but its assumptions are often very different, and resulting price range may be much wider.
Alternatively, it is to look at the company’s earnings, growth rate and cash flow, order book, competitors, valuation yourself.
Investment Disclaimer
This general information is provided for education and information purposes only.
This is not financial advice and no recommendation as to whether you should buy or sell Netweb Technologies.
Share prices can move significantly because of company results, valuation changes, market conditions, economic events and investor sentiment.
Always check the latest company filings and market data before making an investment decision. Consider speaking with a qualified financial professional where appropriate.
Conclusion
The Netweb Technologies share price target 2030 is ultimately a story about earnings growth rather than a single number.
The company has several attractive long-term opportunities. AI infrastructure is now a major part of its business, while high-performance computing, private cloud and data-center demand provide additional avenues for growth. Its latest quarterly numbers and order book show strong momentum.
But the next four years will test whether that momentum can scale.
For the bullish case to work, Netweb needs to keep winning AI and HPC business, execute projects efficiently, protect margins and turn revenue growth into strong cash-generating earnings. If growth slows sharply or the market reduces the valuation premium attached to AI stocks, the result could be very different.
That is why the ₹5,000, ₹7,000 or ₹10,000 type of target should never be treated as a guaranteed destination. The more useful approach is to keep updating the underlying assumptions.
The company’s quarterly results will tell us much more than any static 2030 forecast.
Netweb Technologies Share Price Resource Hub
Learn everything about Netweb Technologies shares, including the latest share price, price targets, historical performance, stock analysis, quarterly results, and factors to consider before buying or selling the stock.