
Last Updated: September 4, 2026
Introduction – Netweb Technologies Stock Analysis
An effective Netweb Technologies stock analysis should look at factors other than the stock’s daily price. Of course, the key questions to ask are: are they growing; where is the growth coming from; are they profitable and does the current valuation discount too much future growth?
Netweb Technologies’s sector is high-performance computing, AI systems, private cloud and data-center infrastructure. That places the company in a corner of the technology market which is a beneficiary of growing demands on the need for computing power.
Latest earnings are clear indication of investor’s focus. Netweb’s revenues stood at ₹819.6 crores in Q1 FY 27 as against ₹301.2 crores in same period last year. Profit after tax stood at ₹85.32 crores as against ₹30.4 crores. Of the total revenues, AI Systems business contributed roughly₹510.57 crores (62.29%) and witnessed a growth of 484.2% YoY. Order book was approx ₹2,507 crores as on 30 th June 2026.
These figures are very impressive, but should also prompt a healthy question how much of this already is factored into the stock’s price?
This article is for educational and informational purposes only. Not financial advice nor a recommendation to buy or sell Netweb Technologies stock.
Table of Contents
What is Netweb Technologies?
Netweb Technologies is an Indian manufacturer and provider of high-end computing solutions.
Its main areas include:
- High-performance computing
- AI Systems
- Private cloud
- Enterprise computing
- Data-center infrastructure
- Solutions for storage and networking
The company conducts business with the industry customers on IT and IT-enabled services, BFSI, national data center, government, defence, education, and research agency.
What is interesting with the company is that he is dealing with a couple of areas that require huge amounts of computing power.
And AI is the simplest example.
It takes huge servers to run and train high level AI models, along with GPU, networking, storage and infrastructure. This is what the business of Netweb is all about.
The Three Main Growth Areas
Netweb has repeatedly highlighted three important business pillars:
High-Performance Computing
The HPC systems are designed to run the high demanding jobs which common business computer can’t perform easily.
They can be used for:
- Scientific research
- Engineering simulations
- Weather modeling
- AI workloads
- Large-scale data analysis
Private Cloud
The private cloud infrastructure is a platform providing companies the possibility to have cloud-like computing within a tightly controlled place.
This might be beneficial for larger businesses and organizations that need more of command over the infrastructure and the data.
AI Systems
Currently, AI Systems is the most rapidly expanding division of Netweb.
Source: Annual Report FY21, Segment wise numbers (arising from net sales) in FY21Q4, which is calculated as the sum of the following; generation cost, UAS, B&EE, and SG&A. 8 In FY27Q1, the segment heldgenerated around 10.57 crore, accounting for over 62% of operating income. This increase was 484.2% on-year.
Which definitely puts AI at the centre of the company’s current investment story.
Financial Growth
The fast growth of the company is easily demonstrated by the numbers Netweb reports yearly.
| Financial Year | Net Sales | EBITDA | PAT |
| FY23 | ₹444.97 crore | ₹70.69 crore | ₹46.94 crore |
| FY24 | ₹724.08 crore | ₹114.42 crore | ₹75.90 crore |
| FY25 | ₹1,149.02 crore | ₹169.40 crore | ₹114.47 crore |
| FY26 | ₹2,183.56 crore | ₹303.68 crore | ₹205.82 crore |
The yearly figures reflect FY26 was a significant jump. Net sales were nearly two-fold to FY25 levels, while PAT went up to around 205.82 crores.
This is the aspect of the story that makes the company valuable from a basic perspective.
Investors should be cautious as to the condition that growth goes at the same rate forever.
What makes the growth from ₹1,149 crore to ₹2,184 crore so impressive is how much bigger the company already is. It is increasingly difficult to sustain phenomenal growth at such a large base.
Q1 FY27: The Growth Accelerated Again
Of course, the most recent quarter is another positive datapoint.
| Metric | Q1 FY26 | Q1 FY27 | Change |
| Revenue | ₹301.2 crore | ₹819.6 crore | +172.1% |
| PAT | ₹30.4 crore | ₹85.3 crore | +179.9% |
| AI Systems revenue | — | ₹510.6 crore | +484.2% |
The company’s best quarter ever, according to management.
Rather, the more interesting thing is not the fact that revenue grew but the fact that the growth originated from.
AI systems have been the biggest contributor to theCompanies growth.
Which means that investors should approach Netweb, in a different way.
Order Book and Business Visibility
On the 30 th June 2016, Netweb had an order book of nearly about at 2,507 crores.
An order book can give some insight into upcoming revenue, but is not the same as cash earned.
Investors should ask:
- What is the time frame for fulfilling these orders?
- What kind of margins will they be.
- Is there are ordering of jobs (i.e. are the new jobs replacing the finished jobs?)
- How much shopping is due to repeat customers?
- Is it expanding in tandem with the order book?
This is important because Netweb’s operation has the potential for large strategic projects, which can significantly alternate each quarter.
Once again, our earlier Q3 FY26 company research update, published in May 2024, showed the company’s annual organic book size was approximately Rs 525.8 crore with an order flow pipeline of much larger Rs 4,270 crore (not including signings which include L1 projects).
The size and time span of projects must be taken into account when examining quarterly indicators.
AI Is Now the Core Investment Story
The company’s engagement with AI must be the main driver of investor interest in Netweb.
Management stated in the Q1 FY27 update that the demand for AI infrastructure is being led by the IndiaAI Mission, sovereign AI computing, neocloud providers and the cloud service providers.
The previous company documents have indicated higher growth for the AI division as well. In H1 FY26 AI Systems represented 25.4% of revenue, relative to 14.7% in H1 FY25.
By Q3 FY26, AI Systems accounted for a majority of the quarterly revenue at approximately 64.2%.
You shall get compensation over time. The value of your work will decrease. As your skills diminish, the less effective your work will be and the more reluctant you will be to do it. This is a good thing. This is an important progression.
Indicates that netweb’s operating mix has dramatically changed at a fast pace and future achievement could rely partly on the volatility of the AI infrastructure industry.
Why This Matters for Investors
The opportunity is there: as long as Indian AI infrastructure spending (a big part of Netweb’s market) stays robust, Netweb can tap into that.
But there is also another side of the same coin.
The more vital artificial intelligence becomes to the company, the more it gets sucked into the cycles of spending on artificial intelligence.
That means investors need to watch both:
AI demand
and
The capacity of Netweb to profitably run the business.
It’s great to get a large AI order, but what ultimately matters are whether it’s generating a viable flow of revenue, good margins and cash.
Netweb Technologies Stock: an analysis of valuation, profitability, cash flow and competitors for 2026.
The biggest question that arises once you look at the Netweb Technologies which it has achieved is whether the quality of the growth is strong enough to justify the valuation at which the company is trading at.
The answer is mixed and this what makes the stock interesting.
20th Century On the one hand, revenue and profit are increasing very fast, AI Systems has become a huge company, and the return ratios are impressive. On the other hand, the stock is too highly valued, working capital is still playing an important role, and investors are already pricing in significant future growth.
Profitability: Strong Growth with Healthy Margins
Netweb has reported profits that are proportionate to the growth in revenues.
For FY26, the company reported:
| Metric | FY25 | FY26 | Change |
| Revenue | ₹1,149 crore | ₹2,184 crore | ~90% |
| EBITDA | ₹160 crore | ₹285 crore | ~78% |
| PAT | ₹114 crore | ₹206 crore | ~80% |
| EBITDA Margin | 13.9% | 13.0% | Lower |
| PAT Margin | ~10.0% | ~9.4% | Lower |
The FY26 numbers are based on the financial data and published research of the respective company
The key here is that in FY26 revenues increased at a far higher rate than EBITDA and PAT. In other words, scale increased dramatically with no concomitant expansion in margins.
That is not necessarily the case. Large strategic projects can command different margins than a company normally earns.
However, it is another factor investors need to keep an eye on.
Q1 FY27 Was Even Stronger
Was a lost cause by the time June 2026 quarter.
Netweb reported:
- Revenue of ₹819.6 Crore
- Tapairê. Clearly listed as emerging. Nothing in the disclosures gives us insight into examining this company. Total 85.32 crore PAT.
- AML14.7% EBITDA margin
- 10.4% PAT margin. As displayed below, the remaining 10.4% of the PAT margin was obtained through relatively small changes in each expenses which were all in the same direction.
Revenues increased 172.1% YoY while PAT increased 179.9%. ICICI Securities added that the quarter was ahead of its estimates and pointed out the strong HPC/AI and enterprise workload growth.
It’s very positive to see an improvement in margins compared to FY26.
However, one quarter isn’t enough of a sample for determining a long-term trend. The following few results will clarify whether those margins are sustainable.
Balance Sheet: One of the Company’s Strengths
Netweb’s balance sheet looks relatively comfortable.
According to a report by Motilal Oswal published in January 2026, the company was debt free with net cash of around₹1.9 billion as of December 2025.
A preceding research model demonstrated also borrowings at comparatively very low percentages with respect to the company’s net worth.
This matters because a company with little debt has more flexibility when it wants to:
- ADD new capacity to the existing one that is already in place
- Build inventory
- Expand manufacturing
- Fund research
- Handle temporary working-capital pressure
Helped minimize the danger that increased interest expenses will erode profits.
Cash Flow Needs More Attention
There is a matter of investment that forces beyond the investors’ view.
In fast-growing infrastructure businesses there is often considerable need for working capital, such as having to pay suppliers for inputs and start building systems prior to receiving the total (marginal) cash flow from customers.
Netweb has been through this as it has grown up.
A former company research report also indicated large working-capital needs, such as an increase in inventories and receivables as the company grew.
The FY26 ICICI research report, on the other hand, showed a significant change in operating cash flow of ₹1,026 million of reported operating cash flow in its financial model of FY26 of ₹1,715 million before the adjustments. Also, it forecasted positive Free Cash Flow of about ₹1,610million for FY26.
The takeaway is simple:
Growth is positive; however, investors should be concerned if the growth is generating cash.
Return Ratios
Return ratios measure the efficiency of a firm using the capital invested by shareholders as well as operating assets.
A recent market screen showed Netweb with approximately:
- ROCE: 37.5%
- ROE: 32.8%
Actual numbers are subject to fluctuation as additional financial numbers are added. (Screener)
Those are some pretty strong numbers.
High returns are most attractive when tempered by real business expansion rather than borrowed cash.
Valuation: The Biggest Question
This is where the analysis gets more complex.
Netweb enjoys rapid business growth, however investors are already paying through the nose for that growth.
We placed a recent market screen showed the stock at around 117x trailing P/E using information on the market at that point.
ICICI Securities used a 66x one-year forward P/E in its July 30, 2026 valuation and assigned a ₹5,360 target price. The brokerage said it raised the multiple because of stronger performance and higher growth expectations.
These numbers tell us something important.
The market is not valuing Netweb like an ordinary server manufacturer.
Investors are paying a premium because they expect:
- Strong earnings growth
- AI infrastructure expansion
- High returns
- Continued order wins
- Long-term technology adoption
That can work very well when the company meets or beats expectations.
It can also make the stock vulnerable when expectations are missed.
AI Infrastructure Gives Netweb a Differentiator
The most competitive argumentestablished in the companystrategyis its advantage in high end computing infrastructure.
It does not offer merely a hardware product.
Netweb works across areas including:
- AI Systems
- HPC
- Private cloud
- Data-center infrastructure
- Enterprise computing
- Storage and networking. The authors presented four types of storage for their own use and for client sites and discussed the advantages and disadvantages of each. They also looked into small home networking systems and proposed solutions.
That wider product mix might be able to cater for customers with higher complex needs.
The company’s order book indicates the size of the opportunity. ICICI Securities stated that the pipeline stands at Rs.10,410 crore (up 151% YoY) after having a good Q1 FY27.
A pipeline isn’t the same as an order book, and an order book isn’t the same as revenue. Investors should remember those points.
Competitive Position
Netweb is competing in a market against Denik, enterprises and international companies.
Its advantages include:
Local Manufacturing
Can be used when customers require local support for their computing infrastructure.
Technical Expertise
Has knowledge of HPC and complex environment.
AI Exposure
The move to AI infrastructure has created a much larger market than traditional enterprise computing.
Existing Customer Relationships
Conversely, solid relationships with institutions, business and technology partners increases repeat business.
But these benefits are not forever.
Companies of greater size simply have more financial resources, and the AI infrastructure market is growing rapidly.
Main Strengths and Weaknesses
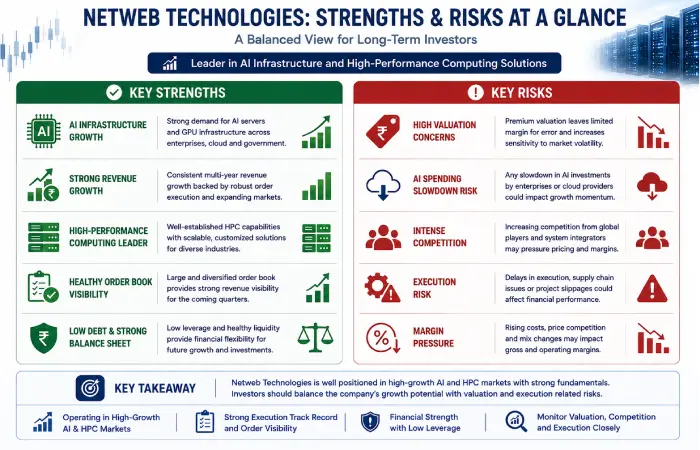
| Strengths | Risks / Weaknesses |
| Laws and regulations necessary for the operation of the business. Very strong revenue growth; | High valuation |
| Rapid AI Systems expansion | Expect this isn’t their major concern. |
| Recent robust profit growth | Experience with the frequency of AI spend cycles |
| Existence of low debt / strong balance sheet | Working-capital requirements |
| High ROE and ROCE | Strong competition |
| Vast order book and pipeline | Execution risks, which include any risks related to the execution of the project (who is involved, the method of execution, the time frame, the location), are also taken into consideration. |
| Poisoning from HPC using for instance HPC7, and data centers; | Margins may differ by project |
That’s why Netweb is not a straightforward “good stock” or “bad stock” case.
Business fundamentals are good but the high valuation requires continued growth from investors.
What Really Counts Now?
For the next few quarters, I’d focus on five things:
- AI Systems revenue
Is this part still expanding at a high rate? - EBITDA margin
Does the company able to keep margin and grow at the same time? - Order book conversion. Customer (residential, commercial, etc) buy house or query a house, and they conduct an order book conversion from a customer’s order to a PMS order. After conducting an order book conversion, the customer or query remains.
Are large orders converting to revenue on time? - Cash flow
What does the cash flow look like? Ascertaining that profit is moving into cash. - Valuation
Is the share price outpacing the rise in the company’s profits?
The five measures should mean a lot more to investors than just short-term movements in the share price.
2013 stock analysis of Netweb Technologies 2026: Outlook, Risks & what investors should keep in mind
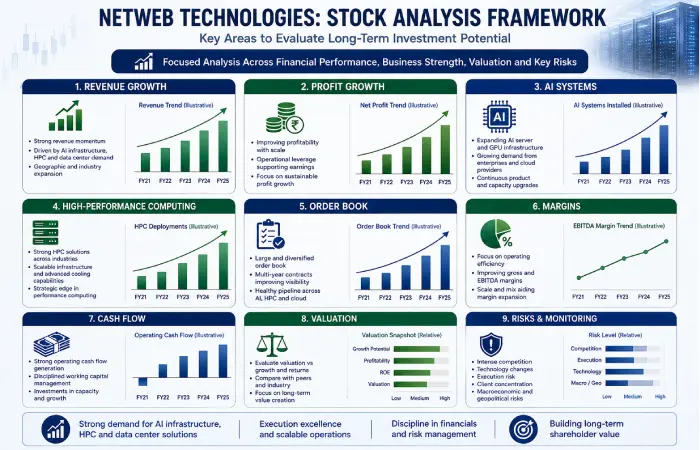
The recent figures show the Netweb Technologies story to be positive, but there should be more to a good stock analysis than just showing revenue increase.
The company is expanding rapidly. The more difficult question is whether it can sustain growth fast enough to support the valuation investors have placed on it.
That is when the subsequent few quarters become crucial.
What Might Keep Netweb Growing?
AI Infrastructure
For Netweb, AI is now the biggest story of growth.
As on Q1 FY27, the revenue from the sale of AI systems (which includes AI Accelerators and Hardware/ Software) was approx.626.32 crores (approx. 510.57 Crores, or 62.29% of revenue. with Y-O-Y increase of 484.2%.
The company has highlighted availability of order from demand coming from indiaAI Mission, sovereign AI computing, neocloud service providers and cloud providers.
This will give Netweb access to a market which could be prevalent for many years to come.
High-Performance Computing
While most of the focus is on AI, HPC still makes up a significant part of the company.
High-performance computing is used for:
- Scientific research
- Engineering
- Weather modelling
- Defence
- Large-scale data analysis
This provides Netweb with another source of demand in the event that the AI industry eventually retires.
Data Centers and Private Cloud
Increase in demand for physical compute infrastructure to support the proliferation of Cloud services and AI workload.
That creates opportunities for Netweb in:
- Servers
- Storage
- Networking
- Private cloud
- Data-center infrastructure
The expansion of product range might prevent a company from being entirely situated on a single market position or type of customer.
Is There Anything That Can “Damage” the Investment Thesis?
A vibrant business can be a very bad investment if the price is already assumed too much growth.
The risks include:
High Valuation
Perhaps the greatest issue.
ICICI Securities arrived at a target of 5360. By applying 66x one-year forward P/E in July 26.,
A high multiple a multiple… signals that investors are already paying a premium for growth, it does.
That leaves less open for disappointment.
The share price might also decline if results are not what were anticipated, even if the business continues to make a profit assuming there is no change in the dividend policy.
AI Spending Could Slow
However, if the breakthroughs that the current AI boom are providing for Netweb also become a risk for the company.
If companies cut back on the budget allocated for AI infrastructures, significant projects could be canceled or postponed.
That could affect:
- New orders
- Revenue growth
- Capacity utilisation
- Profit growth
Hence, investors should be cautious to follow only actual orders and revenues, rather than predicting the AI bubble to persist at this rate.
Competition
Netweb is in a competitive and emerging technology market.
Multinational companies have vastly more finances and R& Dsupport, and Indian companies are also starting developing domestic computing and data-center solutions.
Competition could affect:
- Pricing
- Margins
- Customer acquisition
- The cost of product development.
Though the manufacturing and technical capabilities of Netweb are advantages, one should maintain those advantages.
Execution Risk
According to Moneycontrol, Netweb’s order book as at June 30, 2006 was about? 2,507 crores.
That’s useful visibility, but an order book is not the same as cold hard cash in the bank.
The company still has to:
- Construct the systems.
- Deliver them.
- What were you doing? Finish the projects.
- Recognise the revenue.
- Gather all the money.
If current it any delays can have an impact on quarterly results.
Margin Pressure
High acceleration of revenue growth is inadequate if highly profitability deteriorates rapidly.
ICICI Securities stated that the company’s Q1 FY27 EBITDA margin stood at around 14.7%. The brokerage team felt that this is a good number, though margins are dependent on mix and timing of large projects.
This makes EBITDA margin an important figure to monitor following each quarterly result.
What Investors Should Watch Every Quarter
Investors, instead of daily stock price information, may consider tracking a fixed set of numbers.
| Metric | What It Tells You |
| Revenue growth | Has the business continued to grow at a fast pace? |
| AI Systems revenue | Is the demand for AI still present? |
| PAT growth | Are shareholders receiving the growth? |
| EBITDA margin | Ha, the company protecting profits? |
| Order book | How much future work is scheduled? |
| Order execution | Hell of yes!54 of projects is delivered on time 48 (87%) are delivered on schedule, and 6 (11%) are delivered early. Only 9 of the projects (16%) are late. |
| Cash flow | Is the profit, shown in the accounts, going into the cash? |
| Customer mix | Is the business more diversified? |
| Valuation | Is the stock becoming too costly based on its earnings? |
Which is also a better way to follow Netweb than responding to each daily variation.
Is there anything, in particular, that would take this stock from being a ‘Bad investment’ to a ‘Good investment’?> If the above chart had shown that with five years of excellent growth (as well as the time period included in the chart) the stock had still made negative returns, then this would have been an attractive stock, although this makes it very risky so it is unlikely.
The investment case would become stronger if the company continues to show:
- Strong AI Systems growth
- (High margin) new orders Then, the quantity of orders is multiplied by the durability of the medical devices to get the high-quality new orders.
- Consistent margins
- Rising earnings
- Good cash generation.
- More customers
- Ongoing product development
- Growing the HPC and data-center group
The main positive indicator would be solid growth, with margin and cash flow stable.
So, would a World Government make investors less risky?
Well, there is reason to believe that it would not. After describing the advantages of international regulation above, Beck believes that economists who favor it have failed to seriously consider the following: first it remains to be seen whether the benefits of an international regulator could outweigh the immense costs. Second, in what circumstances such a regulator would produce higher global welfare than the current balance of power?
The warning signs would be almost the opposite:
- AI order growth Is an all-in-one device and to test the product itself has made that wow to the rush of the growth of the cut/ selection. If the hotel lobby it’s good raw material in.
- Revenue rise is relatively more recorded.
- The margins go down several quarters.
- Execution of order is delayed
- There is a surge in working capital.
- The cash flow decline not followed by profits
- Valuations stay elevated and forward earnings expectations decline
No single weak quarter doesn’t alterthe long-term trend story, but a string of weaker quarters would be more significant.
Frequently Asked Questions
Is Netweb Technologies fundamentally sound?
The company currently has good revenue and profit growth, large AI exposure, a healthy order book and good recent return ratios. However, due to its very high valuation, investors have to pay for a lot of future growth too.
What is the main revenue driver for Netweb Technologies?
AI systems is the biggest contributor to growth currently., and in Q1 FY27 contributed approximately 62.29% of the operating revenue and grew at a pace of 484.2% over the last year.
Is Netweb Technologies costly?
Compared to many large-caps and established firms, the stock currently commands an extremely high multiple using conventional measures of valuation. As per the July 2026 valuation, ICICI Securities used a 66x forward P/E.
There is simply nothing we can say about that and it depends entirely on the future revenue flow growing fast or not.
What is the major threat facing Netweb Technologies?
The greatest risks are slowing of AI infrastructure investment, high valuation, stronger competition, implementation issues on projects, and squeezed margins.
Would you buy Netweb Technologies shares?
One stock analysis just can’t give you that for each investor.
The right decision depends on factors such as:
- Investment horizon
- Risk tolerance
- Valuation
- Portfolio size
- Expected returns
- Personal financial goals
Investors should research some of the latest figures and do they own research.
Investment Disclaimer
This article has been published for the information and education of our viewers only.
This is not a financial advice and it does not propose purchase, retention, or sale of Netweb Technologies stock.
Financial markets can be volatile: results, valuation, economic climate and Investor mood can all impact share price.
Always do thorough research of NSE/BSE latest data, company’s financial statement and reports before taking decision to invest or buy/sell any funds. Seek advice from expert financial adviser if needed.
Conclusion
Netweb Technologies has scripted a strong growth story around AI Systems, high-performance computing, private cloud and data-center infrastructure.
The latest figures would do the bullish side of that story justice. while revenue grew 172.1%8yoy to a point just short of ₹819.6 crore, Q1 FY27 PAT was up 179.9%9yoy to a point just shy of ₹85.3 crore, of which AI Systems, alone, accounted for over 62%10.
But the stock is not without risks:
The market is already pricing in a lot of upsides. A high valuation requires the company to continually generate strong earnings, and competition, project execution, margins and AI spend are all significant risks.
So, it’s an intriguing growth-stock story for Netweb, but not an easy one:
The key to following the company is simply to ignore the noise of short-term price action and instead focus on the underlying business. Investors should be monitoring the revenue, growth of the AI Systems business, the execution of the orders, margin expansion, cash flow and valuation.
The next quarterly result will be more valuable than any individual stock-price forecast.
Netweb Technologies Share Price Resource Hub
Learn everything about Netweb Technologies shares, including the latest share price, price targets, historical performance, stock analysis, quarterly results, and factors to consider before buying or selling the stock.