
Last Updated: September 4, 2026
Pros, Benefits, Risks and Disadvantages of Buying Netweb Technologies Shares in 2016? Should You Invest in Netweb Technologies in 2016?
The reason shareholders have been so interested in Netweb Technologies or simply put there is very high growth rate achieved by that Netweb Technologies company and one of the largest driving force behind such high growth rate would be artificial intelligence infrastructure.
However, a fast-growing company in itself is not necessarily a good buy at any price.
That is the main question investors need to answer before buying Netweb Technologies shares:
Is the future growth of the company going to be high enough that it is justifiable to investors to be paying the price they are today?
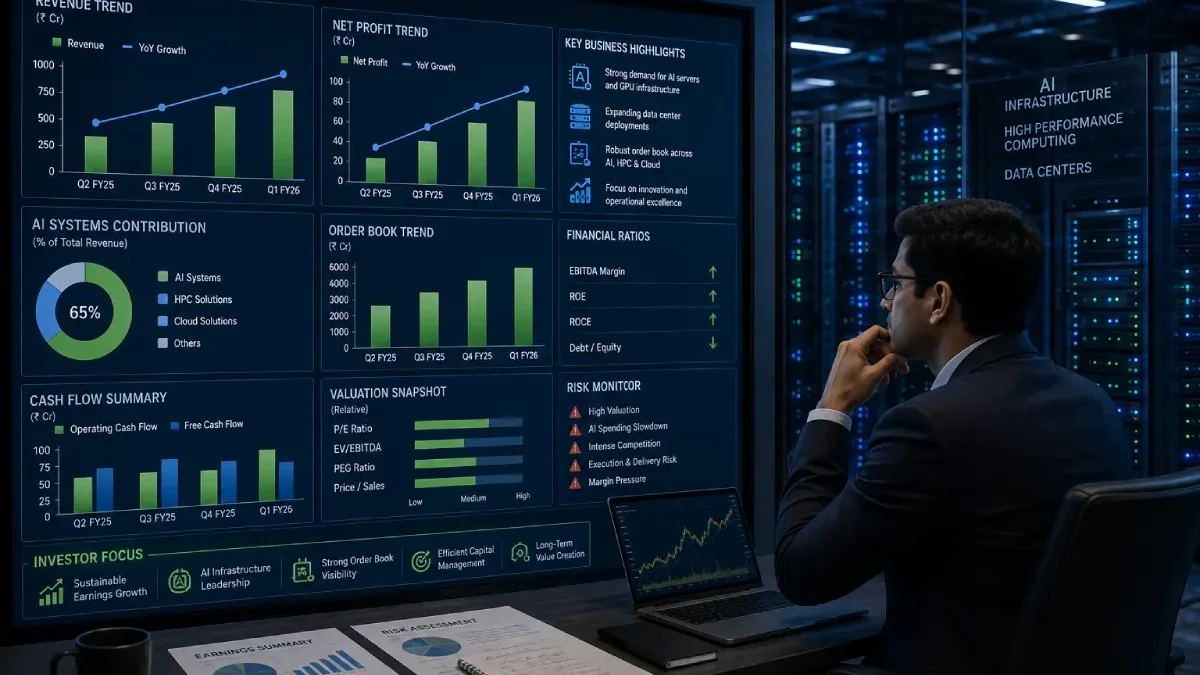
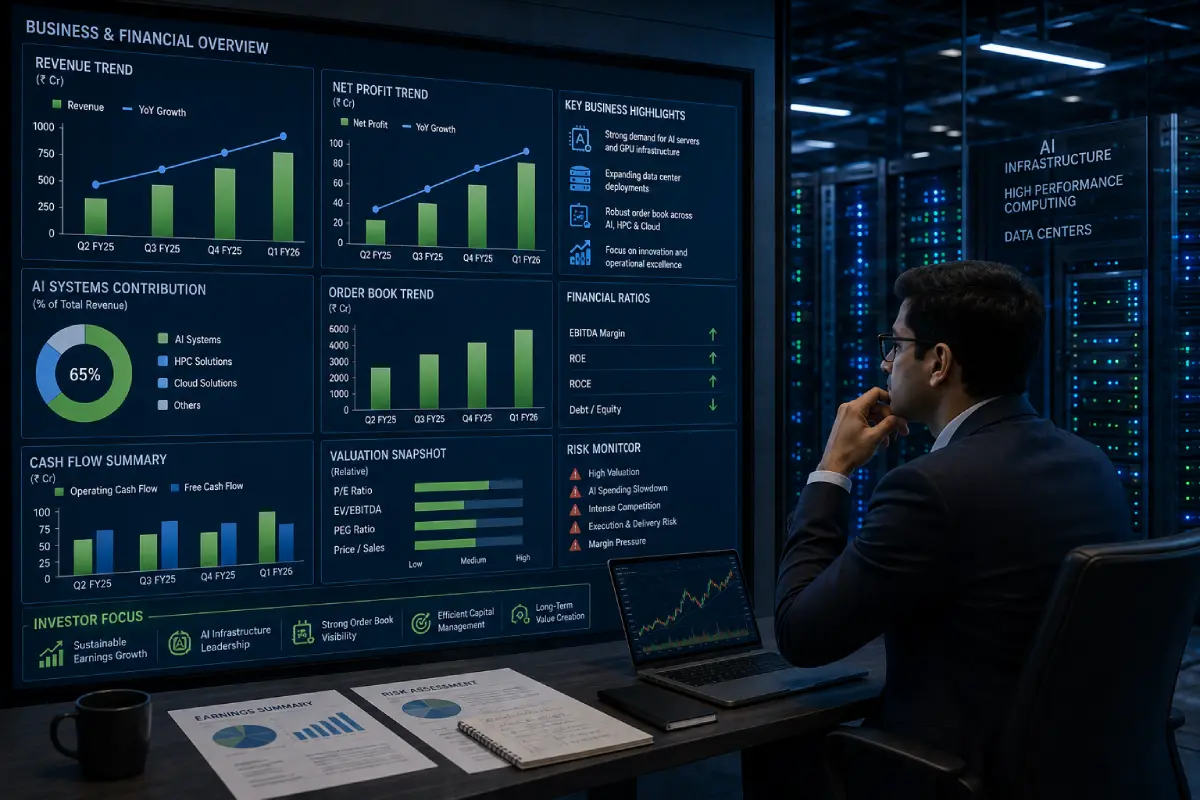
Most recent figures do show an interesting business. During Q1 FY27, Netweb had revenues of approx. ₹ 819.6crore reflecting a growth of 172.13 % YoY and net profit close to ₹ 85.32 crore reflecting a growth of close to 180 %. For Netweb, contribution to all revenue stood at approx. ₹ 510.57 crore (62.29%). Company’s order book stood at approx. ₹ 2,507 crore as at June 30, 2026.
Moreover, the stock is very optimistic. ICICI Securities reiterated a Buy rating in July 2026 with a target of ₹ 5,360 and arrive at the valuation using a 66 x one-year forward P/E.
So there are certainly some good reasons to be interested and there are some good reasons to be cautious.
Investment disclaimer: The content of this article is for information and education only. It should not be taken as financial advice and no recommendation to buy or sell Netweb Technologies stock is made. Please check recent data and consider your own risk levels before investing.
Table of Contents
What makes investors focus on Netweb Technologies?
Over the years, investors have started investing heavily in technology stocks although most investors believe investing in technology stocks is a risky gamble. This is believed to be primarily caused by thestrong FOMO effect [] wherewinners continue to win and losers continue to lose [] andWinners Keep on Winning [] effect. The WKW effect refers to a few big-gainers performing so well that investors are willing to invest regardless of whether the stocks are undervalued or overvalued. In contrast to theWTW effect where technology stocks tend to be so popular that investors are willing to risk everything in the hope of making a gain despite the high probabilities that they will lose too and the initial capital invested will be totally wiped out. However, investors are more comfortable with technologystocks than other stocks and prefer to invest in them.
Why is this so?
One reason is the warm glow investor sentiment concept as it tends to have goodwill, attract high2get there fast’ ratios and there are certain unnatural trends associated with it.
The business is in certain places that are attracting huge amounts of investment.
Netweb works across:
- -i will show a diagram of an artificial intelligence infrastructure7. I believe that for the use of AI in the classroom to be beneficial the infrastructure has to be put into place. This infrastructure I gather will be expensive to put into place as it would need to be during this graduate course. I will justify this in more detail in the implications section.
- High-performance computing
- Private cloud
- Data-center infrastructure
- Enterprise computing
- Storage and Networking.
The biggest reason for the company getting noticed is the AI business.
AI Systems had the highest YoY growth of 484.2% in Q1 FY27 and accounted for more than 62% of operating revenue. HPC and Private Cloud also reported robust contributions of nearly ₹125.3 crore and ₹135.3 crore respectively, to their operating revenues.
Business mix of the company is changing significantly.
Q1 FY27 Shows Why the Stock Is Interesting
Netweb reported its best quarter ever by revenue and profit to management.
| Metric | Q1 FY26 | Q1 FY27 | Change |
| Revenue | ₹301.2 Cr | ₹819.6 Cr | +172.1% |
| Net Profit | ₹30.4 Cr | ₹85.3 Cr | ~+180% |
| AI Systems Revenue | — | ₹510.6 Cr | +484.2% |
| Order Book | — | ₹2,507 Cr | — |
The key point is not the percentage increase but:
It is the fact that AI Systems have become a primary source of real revenue, and not as a long-term business opportunity.
That’s something tangible for investors to look at.
Reason 1: Strong AI Infrastructure Growth
The primary advantage that would make someone turn towards Netweb would be its exposure to the India emerging market for AI infrastructure.
AI models require not just software.
They need:
- Powerful servers
- GPUs
- High-speed networking
- Storage
- Data centers
- HPC systems
Netweb is present in this infrastructure layer.
Company management also cited demand from the IndiaAI Mission, sovereign AI computing, neocloud providers, and cloud service providers as key potential sources of demand in the future.
Thus allowing the company to take advantage of the larger artificial intelligence investment cycle, without having to actually construct one.
Reason 2: Strong Recent Earnings Growth
Although, the latest performance of the company also attracts the investors.
The FY26 revenue was declined to approximately ₹2,183.6 crore compared to around ₹1,149 crore of FY25 while the PAT improved to approximately ₹205.8 crore.
Then there was a big leap again with Q1 FY27.
This is significant, as the investment proposition is not founded solely on a predicted future AI market. The growth is currently visible in the financial results Netweb has reported.
If reaching a milestone equal reaching the end of the road then this question still remains: will this speed be maintained as the company expands?
Reason 3: Large Order Book
The company had ended June 26 with an order book of aroundpocket 2,507 crore.
Being able to see some of future revenues is facilitated by a strong order book.
However investors should treat this figures with suspicion.
An order book is not equivalent to earnings.
The company still has to:
- Run.
- Transport the equipment and systems to the site.
- Recognize revenues.
- Keep within a reasonable range of values.
- Prizes. Get the cash.
That is why the upcoming quarterly results will be significant.
Reason 4: The AI Story Has Real Business Behind It
It’s one thing for a company to just mention AI in an investor presentation and another for them to be actually making billions off AI related products.
Netweb is moving more and more toward the second category.
AI Systems constituted 62.29% of operating revenues for Q1 FY27.
Previous presentations of the company saw the contribution of AI increasing from 14.7% in H1 FY25 to 25.4% in H1 FY26.
This change has happened in a rapid manner.
That’s not to say it guarantees growth going forward, but it certainly makes AI infrastructure one of the most relevant areas to keep an eye on in the company’s subsectors.
Reason 5: Analyst Interest Remains Positive
Major brokerage firms have also expressed positive opinions.
ICICI Securities provided Netweb a Buy rating and a TP of ₹5,360 on 30 July 2026 report. The report pointed to robust HPC/AI growth, a large pipeline, supplier alliances and execution of an IndiaAI Mission-related order.
It’s not meant to suggest that the stock price will hit ₹5,360.
Analyst targets are based on assumptions and those assumptions can change.
Nevertheless, it is nevertheless an indication of the market’s confidence in the long-term prospects of the company that professional analysts are prepared to pay a premium for the share.
The Main Catch: Valuation
This is where it gets a lot more difficult.
A company can have:
- Rapid sales increase
- Message of»Strong profit growth», to be delivered in 2001/2002 by services and products across the board: an outlook of consolidated profits (about € 6 bil.) will first be presented to sell-side in March 2001, with increased growth projections. A full pack of profit measures, of plans and targets on cash flows, P&L, ROE and segment profitability will be targeted for sell-side meeting, due February 2001.
- An expanding AI company.
And could still turn out to be a bad buy if the market has already somehow taken an optimistic view of its future.
ICICI Securities used a 66x one-year forward P/E to value for the period ending July 2026.
This is a very high valuation
Means they are not just paying for today’s earnings. They are paying for a huge amount of expected future growth.
So the share needs to maintain performance.
The market is likely to judge that a lower multiple is warranted if profits growth diminishes significantly.
Part 2
Netweb Technologies Estimated Valuation & Probabilities in 2026. Should You Buy the Stocks?
The main argument in favor of this business is very clear: the business has been growing rapidly since it was created and AI greatly contributed to this expansion.
Now more difficult is to decide if the stock price already alreadys incorporate too much of this success.
At the end of July 2026, Netweb was trading about Rs4,524, with a 52-week range of about Rs1,962–Rs5,244. A consensus of one analyst estimate had an average 12-month target of Rs4,756, on a range of Rs4,110 to Rs5,414.
It, therefore, reduces the margin of error drastically as the stock was not traded that high.
So, the decision is not simply “Is Netweb a good company?” It is:
Is the future growth that is being projected to occur worth the price that is being paid today?
Reasons to Consider Netweb Technologies
AI Is Already Producing Revenue
It’s not a shiny AI story built upon the promises of tomorrow.
In Q1 FY27, the AI Systems business of Netweb accounted for around ₹510.6 crore, or close to 62% of operating revenue. The business was up 484.2% yoy.
This makes AI the company’s biggest engine of growth.
That’s more tangible to investors than seeing “AI” pop up in a company’s deck.
Overall Business Growth Is Strong
According to the latest financials from Netweb, there has been a huge increase in scale.
Q1 FY27 revenue was approximately from and , net profit was approximately from and
That pace of growth can carry a premium valuation with one caveat: as long as the pace of growth lasts.
The Company Has a Large Business Pipeline
Netweb had an order book value of around ₹ 2,507 crore as on 30 June 2026.
A previous research report has also suggested a significantly larger pipeline overall with L1 opportunities indicating the potential demand is likely to be greater than booked orders to date.
Provides a glimpse of what is business to the investors.
But there’s an important distinction:
Pipeline ≠ order book ≠ revenues ≠ profit.
Projects always need selling, delivering, selling again, claiming, invoicing (or raising a claim), selling again, claiming, invoicing (or raising a claim),…
Strong Exposure to Several Growth Markets
Netweb has several technologies that the project relies on in order to run properly.
Its business touches:
- AI infrastructure
- High-performance computing
- Data centers
- Private cloud
- Enterprise computing
This opens up a number of different avenues for growth as the country’s digital infrastructure develops.
Reasons to Be Careful
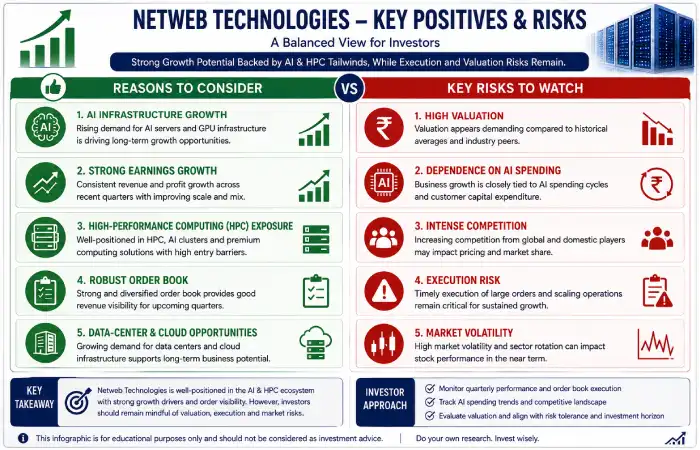
The risks are growing more significant due to the stock’s valuation.
The Valuation Is High
As at late July the stockanalyst.com figure of about ₹4,524, WebNet had a trailing P/E of about 91x and a forward P/E of about 60x on 28th July. The MarketScreener data on the morning of 8th August showed 2026 P/E about 85x, estimated 2027 P/E about 67x.
Those are not normal levels of valuing.
Investors are effectively saying:
“Our earnings of Netweb will increase substantially.”
This can work really well when the results do better than expected.
And when it can go wrong? It can work badly.
The Stock Has Already Had a Large Run
It has been about Rs.1962–Rs.5244.
The first thing is evidenced by:
Firstly, the investors have already discounted the growth of this company significantly.
Secondly, can be high.
Someone who is buying after a large rally is assuming a different risk than the investor who bought early at a far lower valuation.
AI Growth Can Work Both Ways
AI is the company’s largest opportunity, but this also creates reliance on the spending cycle for AI infrastructure.
If companies, cloud providers, or government organizations slow their AI spending, Netweb could see:
- The smaller the majority of the orders: observation of the other factors.
- Delayed projects
- Less revenue growth
- Margin squeeze.10 Reduced profitability is also driving concerns about falling margins. Companies are taking proactive measures to diminish pressures on profit margins by……..
The greater the AI proportion of total revenue, the more inportant this is.
Large Projects Can Distort Quarterly Numbers
The Netweb business includes large strategic infrastructure projects.
That means one quarter sometimes can look strangely hot, because a large project can be working in this quarter.
That’s why it is misleading for investors to annualize an extraordinary quarter as though it were the annual result and suppose the same rate will prevail perpetually.
What is more acceptable is to observe a few quarters simultaneously.
Competition Will Increase
Another reason for the large number of providers also makes a lot of sense in the context of a service it’s a big market.
Netweb has its strengths in local manufacturing, high performance computing competence, and supplier relationships. These advantages do not dissolve competitors.
Over time, investors should watch whether the company can maintain:
- Market share
- Pricing power
- Margins
- Customer relationships
Analyst View
The analyst consensus is more positive at present, but the numbers need to be placed in context:
All consensus came up with four analysts giving the stock a Buy rating, with an average 12-month target of ₹4,756 and estimates ranging between ₹4,110 and ₹5,414.
That target is only a little more than what the price was in the end of July, which was ₹4,524.
So the market may not be counting on another quick doubling from current levels looking at those analyst estimates.
The upside case now relies more on earnings improving to match the valuation.
Who would this stock appeal to?
Long-Term Growth Investor
Netweb might attract investors who are prepared to accept greater risk as the volatility is at the higher end, and who believe that the AI infrastructure market in India will stay healthy for a number of years.
They need to be ready for the situation where the inventory declines, even though the company is still expanding.
Investor Looking for AI Exposure
Netweb gives hands on experience with and allows us to make use of the actual physical infrastructure for AI work rather than just the AI software
This may be appealing for investors interested in getting in on the infrastructure piece of the AI boom.
Who needs to be more careful?
Value-Focused Investors
If number one on your list is buying companies at less than average P/E or price to sales, Netweb is not for you.
Low-Risk Investors
The stock has a wide trading range and so is not suitable for an investor who feels uncomfortable with large variations in the price.
Investors Buying Only Because of “AI”
This is most important.
While AI is a prominent theme, investing in a stock solely because it has exposure to AI can be very risky.
The actual business outcome is still important.
A Simple Risk-Reward View
| Factor | Positive | Risk |
| Revenue growth | Very strong | It is possible that it will be leading to a decline The growth enthusiasm may be waning the herd of growth investors is losing s he herdsmen and the growth stocks will turn out to be value stocks. Growth stocks will no longer outperform the market. |
| AI Systems | Rapid expansion | AI spending cycle. The ideal situations, and what actually happens, are as following: The equation for the determinants of AI investment at an early stage of penetration is that set out in the box on the right. The levels AI investment will reach in markets of different market shares is shown in the left hand box. |
| Order book | Strong visibility | Execution required |
| Balance sheet | Relatively strong | Working capital is still important. |
| Valuation | Premium indicates growth | Lack of space for disappointment. ‘Indications’are many…yet heart is still not satisfied is a world of many opportunities. |
| Industry | Large AI/HPC opportunity | Competition increasing |
| Stock momentum | Strong performance | High volatility |
The image is relatively clear.
Business quality: Strong
Growth opportunity: Strong
Valuation: Expensive
Risk level: High
That’s why two different investors can look at the same company and decide very differently.
The Key Question for 2026
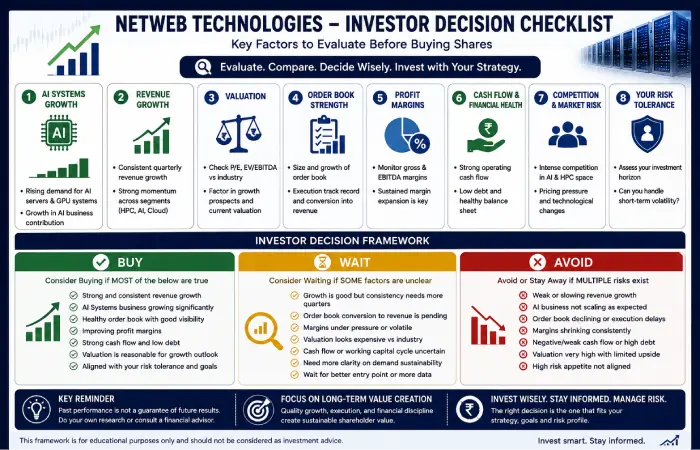
The most useful question isn’t:
Is the value of Will Netweb stock going to increase?
It is:
He can Netweb Nimbis in the profits so quickly as to justify the valuation today?
As long as the revenue and profit continue to grow on the current high rate, the current valuation becomes easier to justify.
When growth declines significantly but the valuation remains high, the stock will be far more exposed.
That is the key issue investors should keep an eye on in the coming few quarterly results.
Is it worth purchasing netweb Technologies shares in 2026? Do you want to know the eight reasons why you should buy netweb Technologies shares in the current 2026?
To decide whether to buy Netweb Technologies shares one has to consider two factors, both of which needs to be looked at together that is, growth plus cost incurred to buy that growth.
Business growth is evidently being witnessed. As per the company the first quarter FY27 revenue was approximately between 818.4 and 820.9cr and net profit was approximately 85.4 cr. AI Systems produced in roughly 510.6cr this is 62.29% of operat ing revenue and for end of June 2026 the order book was approximately 2507cr.
The hard part is the valuation. A recent congra of analyst takes the average stock target of about 5404 as a -up from 4756- but that still implies quite a limited upside relative to the scale of growth already priced into the share.
So rather than giving a simple ‘yes’or’no’, it makes more sense to determine which scenario fits you.
To buy or not to buy?
acheter odder nicht? Should you buy it, wait for it or avoid altogether? Kaufen, warten oder ganz sein lassen?
| Investor Situation | More Reasonable Approach |
| Investor in the long term0. just willing to accept a very high level of volatility. | Consider |
| Investors assured of long term AI infrastructure development in India | Think long term: |
| A value investor seeking lower valuations. | Wait |
| Low-risk investor | Be cautious |
| Investors who buy just for the AI theme | Don’t be too hasty in the various stages. |
| Short-term trader | Para’s largely relies on the level and positioning of the current price 1. when is cheap and would trade on 2. on the current market structure such as, either higher or lower prices around and the current. |
This isn’t a recommendation. Just, the table illustrates that the same stock might be good for one investor and not another.
When the Bull Case Makes Sense
A bullish case becomes more persuasive if Netweb keeps doing those things that initially attracted investors.
AI Systems Keep Growing
AI systems are now the main driver of growth.
In Q1 FY27; it accounted for more than 60% of revenue and its growth was very high.
This key test will be whether that growth persists once these large projects have been progressed.
Revenue Keeps Growing Without a Big Margin Hit
When selling up netweb it is more advantageous if netweb has been making a healthy profit.
Investors should therefore watch:
- Revenue growth
- EBITDA margin
- PAT margin
- EPS
- Cash flow
If a company has a fast-growing set of revenues but then loses money along the way, this is a very different sort of investment.
New Orders Keep Replacing Completed Orders
Based on the period over the weekend the order book looks promising.
But investors should look for a repeating cycle:
New orders > execution > revenue > profit > new orders
This would be a more secure indication that the company is more, in terms of structure, rather than, as mentioned, a single project view.
When Waiting May Make More Sense
Getting a firm isn’t required of that company.
This actually applies very much to Netweb as valuation has become really a key element in the investment discussion.
One of the earlier research reports from H2 2025 clearly stated that ‘a significant fraction of the stock’s upside is already reflected in the share price’, which resulted in a Downgrade to ADD, although the company still has a positive growth.
That is a good lesson.
On the business and buy the stock at the same time.
Waiting may make more sense for investors who want:
- A less optimistic valuation.
- A broader safety margin A wider safety margin
- Another few quarterly results
- Explicit better evidence of profit is catching up with the shareprice.
How could the stock be made more appealing?
The investment case would improve if one or more of these happens:
Earnings Catch Up
If for 3–4 quarters the EPS exceeds the value of the share price it would make the valuation more realistic.
AI Growth Remains Strong
Ai Systems’ continued growth would reinforce the central thesis of the business.
Margins Improve
Greater margins would increase the value of growth.
Cash Flow Improves
A robust cash generation to back up that the reported profits are truly leading to tangible financial strength.
The Stock Corrects Without Business Deterioration
A correction in price driven primarily on sentiment can offer a more attractive entry point if the underlying business is still fundamentally sound.
What would cause me to trust you even less?
I would be very interested if there were a combination of the signs.
AI Growth Falls Sharply
If the growth in AI Systems is much more muted than currently anticipated, the primary story of growth shall be somewhat different.
Revenue Growth Drops for Several Quarters
One quarter isn’t enough of a slowdown. A longer period of slowdown is of more significance.
Margins Keep Falling
A strong sale with decreasing profitability would depreciate the quality of the growth.
Cash Flow Lags Profit
If PAT continues growing while operating cash flow remains unchanged, investors need to find out what is causing this.
Valuation Remains High While Estimates Fall
Perhaps this is the most uncomfortable mixture.
If earnings forecast is revised lower, but the market still values the stock very highly the shares become riskier.
Good questions: What must you check before you get your hands on, say, that new compact disc player?
Before making a decision, check these seven things:
| Check | Question |
| Revenue | How is the growth business? Is demand still healthy? |
| AI Systems | Is the central growth engine still growing? |
| Profit | Is sales growth leading to profit growth? |
| Margins | Is it still profitable? |
| Orders | Is the order book being replenished? |
| Cash | Is the profit turning into cash? |
| Valuation | Shares in pace with profits? |
That is much better than just checking whether the new target is higher than the current price!
Analyst Targets Are Only One Piece of the Puzzle
Analyst Opinions have rebounded; the last six analyst opinions have been positive.
A report from ICICI Securities authored in July 2026 continued to give it a Buy for INR 5,360 target, using a 66x one-year forward P/E.
3.1.5.12 Further analyst compilations. The following was then collected from another group of Analyst compilations as an average target of, (again based on 4 analyst compilations).
These are only targets and are not guaranteed. They can be a good guide to market expectations.
Even more significantly, targets will fluctuate.
A good example is an old ICICI report (from May 2026) with a target of Rs 4,500 and a 56x forward P/E , before the company had yet another good quarter.
That illustrates the importance of investors having the knowledge of the definitions behind the target rather then the target itself.
Who Is Likely to Avoid!
Netweb may not be suitable for someone who:
- Cannot stomach buck swings.
- Is interested in a stock with a low price divided by earnings (P/E).
- Requirement of regular in short term.
- Is uneasy about the fluctuations in the technology sector.
- Is purchasing simply because AI is fashionable.
It is still a good deal, but simply a totally unsuitable investor.
Frequently Asked Questions
Would you Invest in Netweb Technologies Shares in 2026?
You could argue there is not a single answer for all investors. Netweb is clearly growing aggressively and obviously has a lot of its focus on AI infrastructure but has a extremely high valuation while also being very volatile. Or you could say you should evaluate based on volatility, investment timeframe, valuation expectations and financial objectives.
Is Netweb Technologies a worthy long term investment?
The company has attractive long-term exposure to AI infrastructure, high-performance computing, private cloud, and data centers. Whether it is a good investment at any particular price depends on future earnings growth and valuation.
Is Netweb Technologies overvalued?
The stock trades at a premium valuation compared with many traditional technology and hardware companies. That premium may be justified if earnings continue growing rapidly, but it also increases downside risk if expectations are missed.
What is the biggest reason to consider Netweb?
The strongest reason is its rapid growth in AI Systems and its position in India’s expanding AI infrastructure market.
What is the biggest risk?
The combination of high valuation and dependence on continued growth is probably the main risk. If earnings growth slows significantly, the market may reduce the valuation multiple as well.
Investment Disclaimer
This article is for educational and informational purposes only.
It is not financial advice and does not recommend buying, holding, or selling Netweb Technologies shares.
Stock prices can change quickly. Before making an investment decision, review the latest company filings, NSE/BSE data, financial results, valuation, and your own risk tolerance. Consider speaking with a qualified financial professional when appropriate.
Conclusion
So, should you buy Netweb Technologies shares?
The most honest answer is: the business looks much easier to like than the valuation.
Netweb has genuine strengths. Its AI Systems business has grown rapidly, overall revenue and profit have increased sharply, and the company has a sizeable order book. The AI infrastructure market also gives it a long-term growth opportunity.
But the stock has already received a significant re-rating, and investors are paying a premium for future growth. That means the company needs to keep delivering strong results.
For a long-term investor who understands the risks and believes India’s AI infrastructure market will continue expanding, Netweb can be worth considering.
For a value-focused investor who wants a larger margin of safety, waiting for a better valuation or clearer earnings visibility may make more sense.
The key point is this:
Don’t buy Netweb simply because it is an AI stock. Buy only if you understand the business, the valuation, and the risks.
The next quarterly results will tell us more than any single price target.
Netweb Technologies Share Price Resource Hub
Learn everything about Netweb Technologies shares, including the latest share price, price targets, historical performance, stock analysis, quarterly results, and factors to consider before buying or selling the stock.